Where does AI spending go? A revenue map of NVIDIA, AMD, Intel, Bloom Energy and Meta
Follow AI demand from ChatGPT and Meta Muse to data centres, chips and on-site power. Compare current company guidance, implied sequential revenue growth and the risks behind five stock candidates.
Give an AI service a longer job and more computation happens behind the screen. More useful tasks can create demand for servers, chips and electricity. That is why a search for AI stocks quickly leads from a chatbot to semiconductor and power-equipment companies.
Start by separating roles. A service business such as Meta buys computing capacity; NVIDIA, AMD and Intel supply chips, while Bloom supplies on-site power equipment. Connected businesses do not grow revenue or cash at the same pace. Current company guidance helps show the difference.
This reader-requested feature is based on public sources.
Several suppliers stand behind one AI service
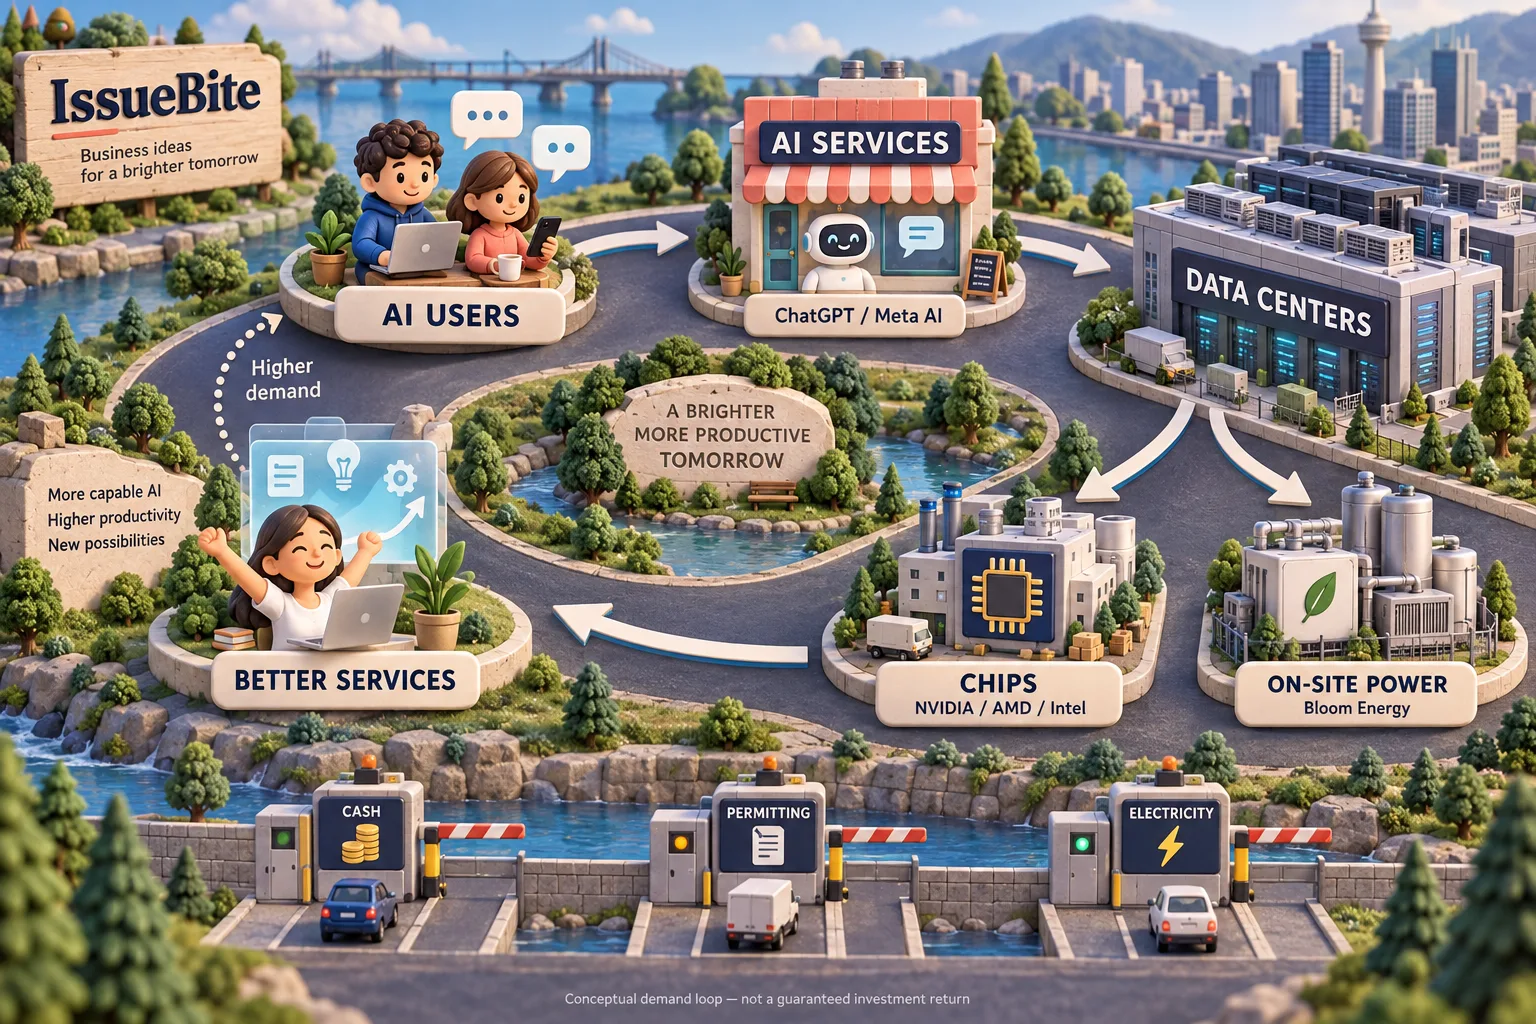
The illustration maps demand rather than a guaranteed cash loop. If customers find AI useful and pay for it, service providers have a reason to add processing capacity. Data centres house that capacity; chips and electricity are parallel requirements, not sequential purchases in a single production line.
An investment thesis must cross three gaps: usage into customer revenue, capital spending into delivered orders, and supplier sales into cash after costs. Free usage could increase a service provider’s computing bill without producing enough income to fund expansion.
Avoid counting the same economic activity twice. A customer’s capital expenditure may become part of a supplier’s sales. Adding both together does not create two independent pools of AI demand. The arrows are neither verified contracts between every named company nor a forecast of stock-price rotation.
 Open full-size visual ↗
What companies expect to sell next
Guidance is management’s outlook, not realized revenue. The table compares each next-quarter midpoint with the latest quarter. NVIDIA’s fiscal Q2 2027 ended July 26, 2026; its fiscal-year label should not be mistaken for a forecast a year further away.
For NVIDIA, the calculation is 108 ÷ 96.221 − 1 = 12.2%. It describes the sales expectation embedded in guidance. It is neither an analyst price target nor an expected share-price return.
Each company is compared with its own latest quarter. This is not a ranking of pure AI sales or share-price upside.
| Company / ticker | Latest sales¹ | Next-quarter range¹ | Midpoint vs latest quarter |
|---|---|---|---|
| NVIDIA / NVDA | 96.221 | 105.84–110.16 | +12.2% |
| AMD / AMD | 11.536 | 12.7–13.3 | +12.7% |
| Intel / INTC | 16.1 | 15.8–16.8 | +1.2% |
| Meta / META | 60.801 | 61–64 | +2.8% |
How to read this ¹ USD billions. NVIDIA latest period: FY2027 Q2; others: calendar Q2 2026. Outlook: each company’s Q3. Midpoints are arithmetic averages, not booked revenue.
NVIDIA and AMD: two different questions behind “chips”
NVIDIA reported approximately $89bn of Data Center sales within $96.221bn total revenue. That makes it a useful first candidate for examining the link between infrastructure spending and supplier revenue. Its next-quarter outlook excludes China Data Center compute sales; supply and export restrictions remain important boundaries.
AMD reported $6.718bn of Data Center revenue, including CPUs rather than only AI GPUs. It is a second research candidate for competitive supply expansion. Prior-year export-control inventory and related charges of $800m affect gross-margin and earnings comparisons, not the revenue-growth denominator. Read the reasons for sales growth and margin improvement separately.
Intel and Bloom: will recovery and installations become results?
Intel guides to $15.8–16.8bn next-quarter revenue. Its roughly $11bn GAAP net loss follows standard accounting rules; the $0.42 adjusted earnings-per-share figure excludes selected items. The adjusted figure does not establish a completed turnaround. Watch operating progress and the cost of capacity expansion.
Bloom is an on-site fuel-cell equipment business, not simply an electricity utility. It reported roughly $1.0654bn quarterly revenue and guides to $3.9–4.2bn for full-year 2026. The question is whether demand for power becomes installed equipment and recognized revenue.
Production capacity, financing, installation and interconnection can alter timing. An order is not yet a completed sale, and fuel cells are not automatically fuel-cost-free or zero-carbon. Compare Bloom’s annual guidance with annual results, not another company’s quarterly outlook.
Against 2025 revenue of $2.023994bn, Bloom’s annual range implies growth of about 92.7–107.5%. Subtracting reported Q1 and Q2 sales, totalling $1.816419bn, leaves roughly $2.0836–2.3836bn needed in the second half. That is a condition for meeting annual guidance, not separate company Q3 guidance.
Meta Muse and ChatGPT: product excitement meets the stock boundary
Meta announced a US rollout of the Muse personal agent on September 8. Muse is the service and Muse Spark the underlying model. The announcement does not establish Korean availability or a measurable contribution to earnings.
Meta reported $60.801bn revenue but $0.784bn free cash flow. Its $130–145bn annual capital-expenditure guidance includes finance-lease principal. Investors need to examine the cash left after expansion, not just product attention. The entire spending figure cannot be assigned to Muse.
OpenAI announced a confidential draft S-1 submission, which is not a completed listing. We did not verify an official tradable ticker or offering price. ChatGPT therefore appears as an AI service in the diagram, not as a directly purchasable stock in the comparison table.
Two research priorities, and three conditions to watch
For understanding the industry through reported results, I would read NVIDIA first and AMD second: the former for the scale and delivery outlook of Data Center sales, the latter for how competitive expansion converts into earnings. That is a research order, not a buy ranking at today’s prices. A valuation and a portfolio’s loss tolerance are still missing from that decision.
For Bloom, watch installation and cash collection; for Intel, realized earnings recovery; for Meta, cash generation after heavy investment. Owning all five does not eliminate a shared vulnerability to a slowdown in data-centre spending. Different business names can still carry a common risk.
At the next earnings release, compare actual sales with this guidance, then examine operating cash flow and the share count. Revenue can grow while fundraising dilutes the claim represented by each share. That is the final step between an appealing industry illustration and a usable investment judgment.
Reader conversation
Community ↗Questions, first-hand results and different perspectives are welcome. Counts reflect real member activity only.
Moderation
Sources and verification notes
- NVIDIA · latest earnings and outlook ↗Checked 2026-09-22
What this source supports
- Several suppliers stand behind one AI service
- What companies expect to sell next
- NVIDIA and AMD: two different questions behind “chips”
- Two research priorities, and three conditions to watch
- AMD · latest earnings and outlook ↗Checked 2026-09-22
What this source supports
- Several suppliers stand behind one AI service
- What companies expect to sell next
- NVIDIA and AMD: two different questions behind “chips”
- Two research priorities, and three conditions to watch
- Intel · latest earnings and outlook ↗Checked 2026-09-22
What this source supports
- Several suppliers stand behind one AI service
- What companies expect to sell next
- Intel and Bloom: will recovery and installations become results?
- Two research priorities, and three conditions to watch
- Bloom Energy · latest earnings and outlook ↗Checked 2026-09-22
What this source supports
- Several suppliers stand behind one AI service
- Intel and Bloom: will recovery and installations become results?
- Two research priorities, and three conditions to watch
- Meta · latest earnings and outlook ↗Checked 2026-09-22
What this source supports
- Several suppliers stand behind one AI service
- What companies expect to sell next
- Meta Muse and ChatGPT: product excitement meets the stock boundary
- Two research priorities, and three conditions to watch
- Meta · Introducing Muse personal AI agent ↗Checked 2026-09-22
What this source supports
- Meta Muse and ChatGPT: product excitement meets the stock boundary
- OpenAI · Confidential S-1 announcement, not completed listing ↗Checked 2026-09-22
What this source supports
- Meta Muse and ChatGPT: product excitement meets the stock boundary
- Bloom Energy · 2025 annual revenue ↗Checked 2026-09-22
What this source supports
- Intel and Bloom: will recovery and installations become results?